Should New York impose its pied-a-terre tax on New York City second homes?
Wilbur Ross, Hilary Geary Ross and Steve Wynn challenge New York's second-home surcharge. Mamdani and Hochul defend taxing wealthy owners to fund city services. The dispute concerns fairness and constitutional limits.
Claim in dispute
Wealthy owners of luxury second homes should contribute more to funding New York City's public services through a pied-a-terre surcharge.
Case period:
Published by The Dispute Index editorial teamPublished Updated
Overview
The enacted tax is based on whether a qualifying property is used as a primary residence, not simply whether its owner lives outside New York State. A city resident's second city home can qualify; a nonresident owner's property can be exempt if a qualifying tenant or immediate family member lives there as a primary residence.
For 2026-27 and 2027-28, the statutory thresholds are $5 million for one- to three-family homes and $1 million for condominium and cooperative units, using Department of Finance valuations. Those valuations are not purchase prices.
A separate September 29 ruling in O'Brien v. New York City addressed tax notices and the supplemental roll, not the statute's constitutionality. The Department of Finance now lists October 13 as the exemption-application deadline.
People in this case
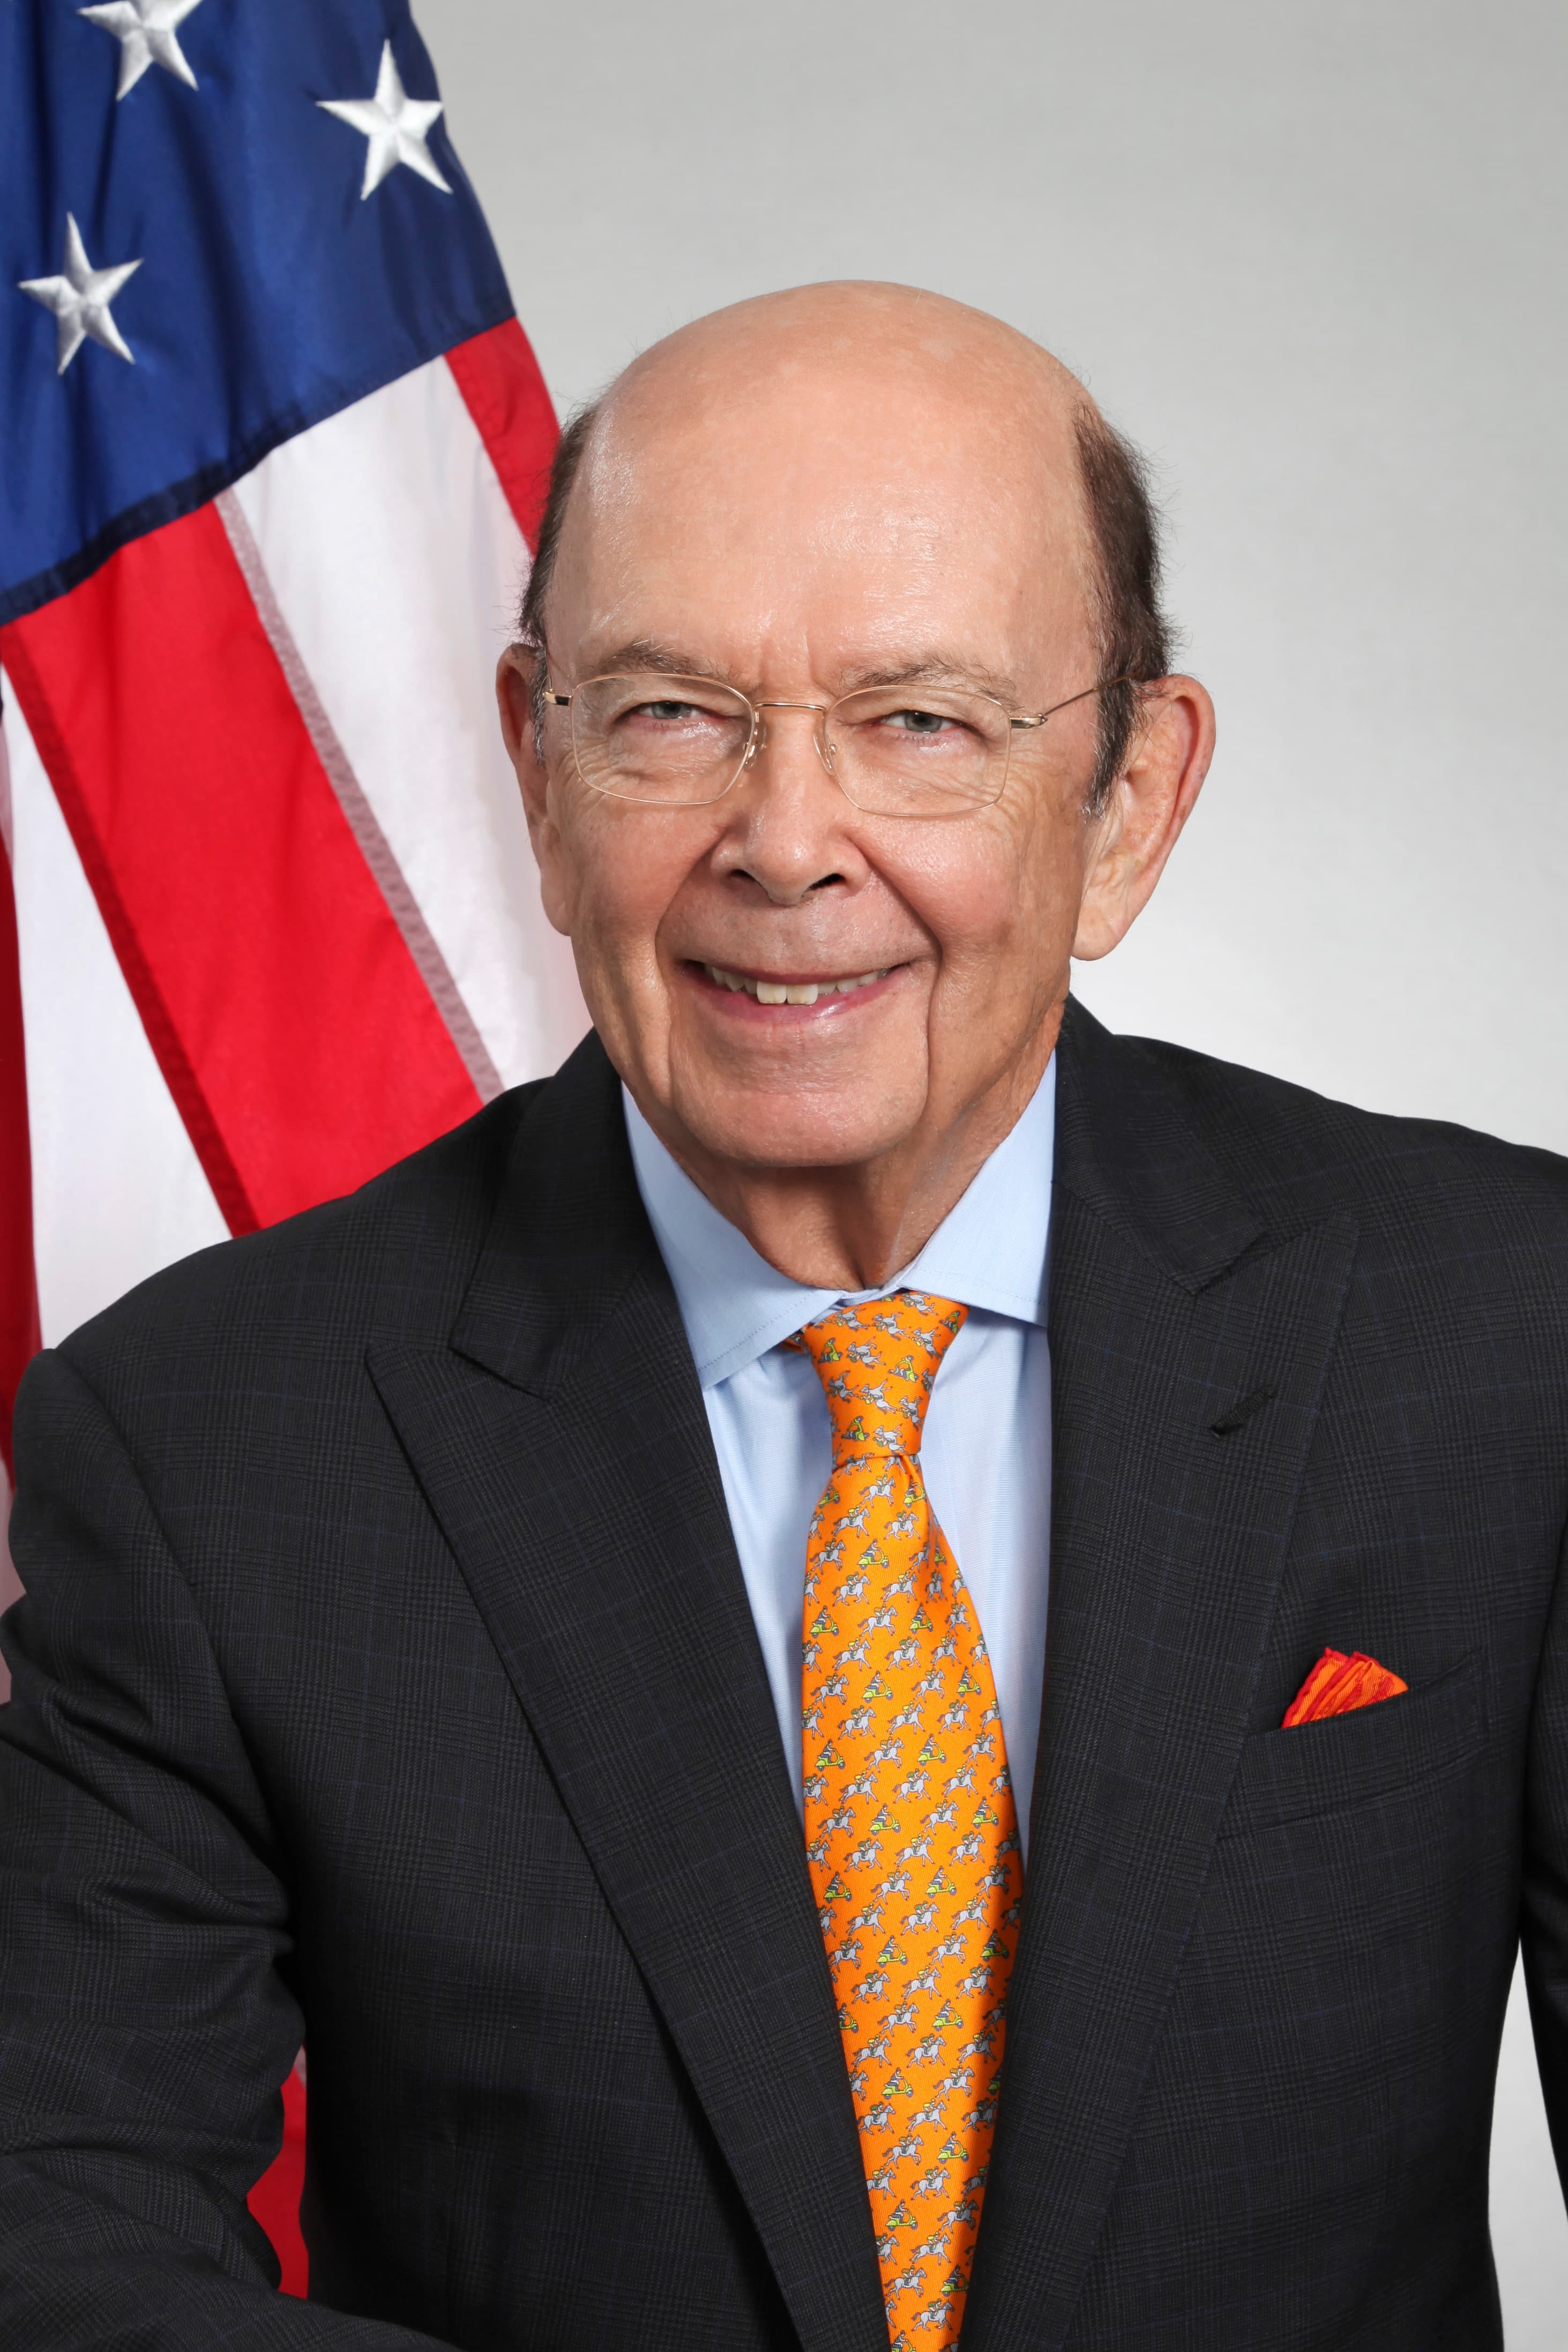 Wilbur RossDirectly involved
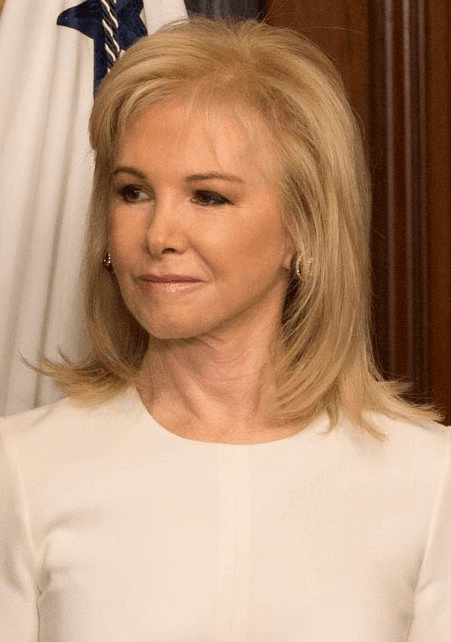 Hilary Geary RossDirectly involved
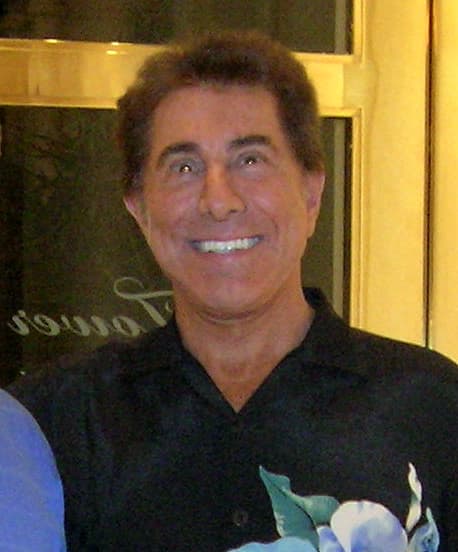 Steve WynnDirectly involved
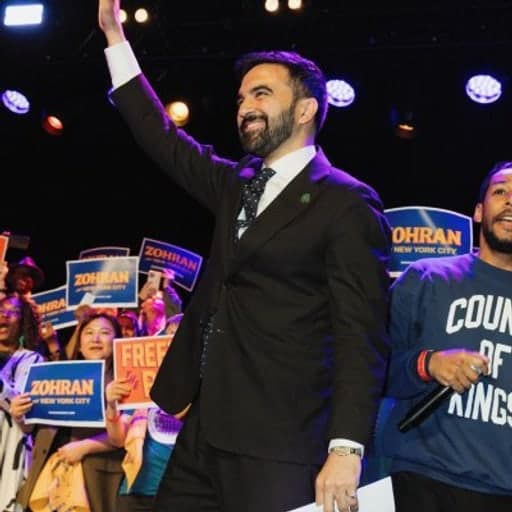 Zohran MamdaniDirectly involved
Timeline
7 timeline entries on this page. Dates: April 15, 2026 to September 29, 2026
April 2026
1 event
Hochul and Mamdani announce the second-home tax proposal
Source release
The governor and mayor propose a surcharge on luxury second homes to raise revenue for city services.
[01]Hochul announces pied-a-terre tax proposal for luxury second homes
April proposal and attributed endorsements. Its proposed $5 million threshold should not be substituted for the enacted phase-one thresholds.
Hochul announces pied-a-terre tax proposal for luxury second homesStatements by Kathy Hochul, Zohran Mamdani, Julie Menin and Brad Hoylman-Sigal.
43 days between recorded events
May 2026
1 event
New York enacts the surcharge
Incident
Hochul signs the revenue legislation adding Article 30-C. The enacted thresholds differ from the initial proposal.
[02]Ross v. New York: complaint challenging the pied-a-terre tax
Source excerpt
This case arises out of Defendant’s attempt to enact and enforce a discriminatory property tax that falls exclusively on nonresidents of New York City, in violation of the state and federal constitutions. … These nonresidents, including Plaintiffs herein, already pay significant sums to the City in property taxes, the same taxes at the same rates paid by New York City residents occupying similarly assessed residential properties. … Article 30-C is therefore unconstitutional to the extent it purports to exclude PAT Tax revenues from the amount raised by tax on real estate for purposes of Article VIII, § 10(e).
Joint pleading alleging unconstitutional discrimination and improper treatment of tax receipts. The plaintiffs' allegations and requested declarations are not a court judgment.
Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.[03]New York Tax Law Section 1350: non-primary-residence surcharge
Enacted provision imposing a surcharge from July 1, 2026. Eligibility depends on use of the property as a primary residence and its statutory market value.
New York Tax Law Section 1350: non-primary-residence surchargeSection 1350, imposition of surcharge and phase-one and phase-two thresholds.
34 days between recorded events
July 2026
2 events
The surcharge's first fiscal year begins
Incident
Article 30-C imposes the surcharge beginning July 1, with phase-one thresholds for qualifying homes and cooperative and condominium units.
[03]New York Tax Law Section 1350: non-primary-residence surcharge
Enacted provision imposing a surcharge from July 1, 2026. Eligibility depends on use of the property as a primary residence and its statutory market value.
New York Tax Law Section 1350: non-primary-residence surchargeSection 1350, imposition of surcharge and phase-one and phase-two thresholds.[04]New York Tax Law Section 1353: surcharge rates
Statutory rate bands. Department of Finance market values are not interchangeable with an owner's purchase price.
New York Tax Law Section 1353: surcharge ratesSection 1353(a), phase-one rates; Section 1353(b), phase-two rates.Mamdani announces initial property-owner notifications
Source release
The mayor's office announces mailed notifications and resources for owners, while defending revenue for parks, schools and libraries.
[05]Mamdani announces notices for the new pied-a-terre tax
Mamdani defends collecting revenue for parks, schools and libraries while announcing the start of notifications.
Mamdani announces notices for the new pied-a-terre taxFirst quoted statement by Mayor Mamdani, beginning with his account of the city's fiscal challenges.
67 days between recorded events
September 2026
3 events
The Rosses and Wynn file their constitutional challenge
Claim
The plaintiffs sue New York State in Suffolk County, seeking declarations against the surcharge and its treatment of receipts.
[02]Ross v. New York: complaint challenging the pied-a-terre tax
Source excerpt
This case arises out of Defendant’s attempt to enact and enforce a discriminatory property tax that falls exclusively on nonresidents of New York City, in violation of the state and federal constitutions. … These nonresidents, including Plaintiffs herein, already pay significant sums to the City in property taxes, the same taxes at the same rates paid by New York City residents occupying similarly assessed residential properties. … Article 30-C is therefore unconstitutional to the extent it purports to exclude PAT Tax revenues from the amount raised by tax on real estate for purposes of Article VIII, § 10(e).
Joint pleading alleging unconstitutional discrimination and improper treatment of tax receipts. The plaintiffs' allegations and requested declarations are not a court judgment.
Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.A separate court order requires new tax notices
Incident
In O'Brien v. New York City, Justice Ozzi orders existing notices cancelled and individualized determinations before new notices. The ruling concerns implementation, not the constitutional merits of the Ross-Wynn complaint.
[06]O'Brien v. New York City: September 29 decision on tax notices
The order addresses the supplemental roll and mailed notices. It cancels the notices and requires individualized determinations before new notices. It does not declare the surcharge statute unconstitutional.
O'Brien v. New York City: September 29 decision on tax noticesIndex 85217/2026, NYSCEF document 34; scope on pages 1-2; ordered relief on pages 21-22.Hochul responds to the Ross and Wynn lawsuit
Reaction
Hochul says Ross and Wynn's objection strengthens the case for taxing luxury second homes.
[07]Hochul defends the pied-a-terre tax after Ross and Wynn sue
Hochul adds her own defense of the tax to a reporter's account of the new lawsuits.
Hochul defends the pied-a-terre tax after Ross and Wynn sue · Kathy HochulFull quote-post of Laura Nahmias's report on constitutional challenges.
Claims
Claims separate what was said from what is contested. Follow each source for the original wording and context.
What's disputed
Disputed claim
Wealthy owners of luxury second homes should contribute more to funding New York City's public services through a pied-a-terre surcharge.
Sources (2)
- Hochul announces pied-a-terre tax proposal for luxury second homesStatements by Kathy Hochul, Zohran Mamdani, Julie Menin and Brad Hoylman-Sigal.
- Hochul defends the pied-a-terre tax after Ross and Wynn sue · Kathy HochulFull quote-post of Laura Nahmias's report on constitutional challenges.
Disputed claim
New York's pied-a-terre surcharge unlawfully discriminates against nonresidents who already pay property taxes.
Sources (1)
- Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.
Disputed claim
The surcharge is a property tax whose receipts must count toward New York City's constitutional real-estate-tax limit.
Sources (1)
- Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.
Arguments
Documented position
Kathy Hochul, Zohran Mamdani and Brad Hoylman-Sigal
Second-home owners can help fund the services that sustain their properties
The tax's supporters say wealthy second-home owners benefit from city services and can contribute more without placing the same burden on working residents.
Limit of this argument
A fairness argument does not resolve whether the chosen tax structure complies with constitutional limits.
Read sources
Sources
- Hochul announces pied-a-terre tax proposal for luxury second homesStatements by Kathy Hochul, Zohran Mamdani, Julie Menin and Brad Hoylman-Sigal.
- Mamdani announces notices for the new pied-a-terre taxFirst quoted statement by Mayor Mamdani, beginning with his account of the city's fiscal challenges.
- Hochul defends the pied-a-terre tax after Ross and Wynn sue · Kathy HochulFull quote-post of Laura Nahmias's report on constitutional challenges.
Documented position
Wilbur Ross, Hilary Geary Ross and Steve Wynn, through their joint complaint
An additional residency-based burden must satisfy constitutional limits
The plaintiffs say they already pay property taxes and that a further burden based on residence lacks a sufficient justification. They also challenge excluding the receipts from the property-tax-limit calculation.
Limit of this argument
These are the plaintiffs' legal arguments, not holdings on the constitutionality of the surcharge.
Read sources
Sources
- Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.
- New York Tax Law Section 1350: non-primary-residence surchargeSection 1350, imposition of surcharge and phase-one and phase-two thresholds.
Response record
Responses
Latest recorded positions: 7. Dates: April 15, 2026 to September 29, 2026
Choose one response filter, or select All responses to see the full record.
7 responses on this page
 Kathy HochulGovernor of New YorkDirectly involved
"they make the case for the pied-à-terre tax better than we ever could."
Defended or excusedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Hochul says Ross and Wynn's objection to paying more on luxury second homes reinforces her argument for the surcharge.
Before the statement
Quote-posting reporter Laura Nahmias's report that Ross and Wynn sued, Hochul writes: "When Steve Wynn and Wilbur Ross cast themselves as sympathetic figures over paying their fair share on multimillion-dollar second, third, fourth or fifth homes,"
After the statement
The quote-post ends with this sentence.
Hochul defends the pied-a-terre tax after Ross and Wynn sue · Kathy HochulFull quote-post of Laura Nahmias's report on constitutional challenges.Why this label?
She defends the tax in direct response to the constitutional challenge.
This label describes the statement's response within the context above.
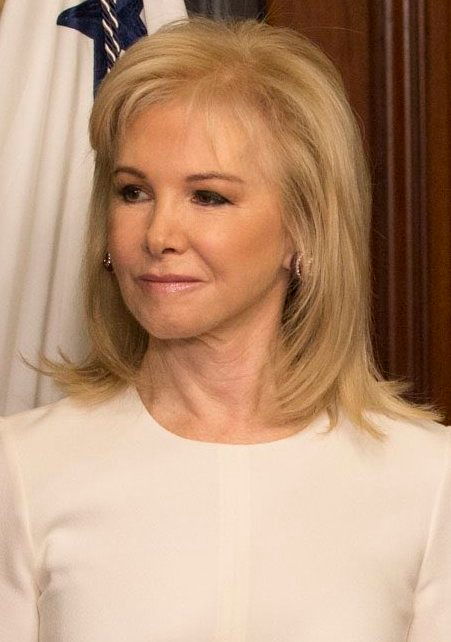 Hilary Geary RossAuthor and plaintiffDirectly involved
"These nonresidents, including Plaintiffs herein, already pay significant sums to the City in property taxes, the same taxes at the same rates paid by New York City residents occupying similarly assessed residential properties."
CondemnedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Hilary Geary Ross joins the constitutional challenge to the surcharge on the Rosses' Manhattan cooperative unit.
Before the statement
The pleading identifies her as a Florida resident and joint owner of the cooperative unit.
After the statement
The three plaintiffs advance a common legal position in one filing.
Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.Why this label?
Her participation in a pleading seeking invalidation is an attributable action opposing the tax.
This label describes the statement's response within the context above.
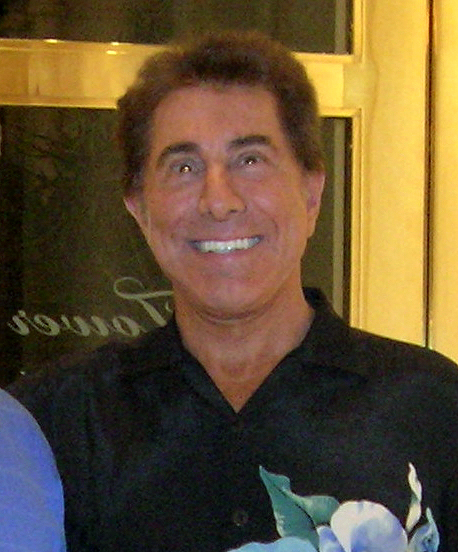 Steve WynnCasino developer and plaintiffDirectly involved
"Article 30-C is therefore unconstitutional to the extent it purports to exclude PAT Tax revenues from the amount raised by tax on real estate for purposes of Article VIII, § 10(e)."
CondemnedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Wynn joins the Rosses' legal challenge, including their argument that lawmakers cannot exclude property-tax receipts from the constitutional tax-limit calculation by changing the label.
Before the statement
The complaint identifies his Manhattan residential property as potentially liable for the surcharge.
After the statement
The tax-limit argument concerns how receipts are counted, not an allegation that the numerical limit has already been exceeded.
Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.Why this label?
He seeks judicial invalidation of the tax and its treatment of receipts.
This label describes the statement's response within the context above.
 Wilbur RossInvestor, former U.S. commerce secretary and plaintiffDirectly involved
"This case arises out of Defendant’s attempt to enact and enforce a discriminatory property tax that falls exclusively on nonresidents of New York City, in violation of the state and federal constitutions."
CondemnedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Wilbur Ross joins Hilary Geary Ross and Wynn in challenging the tax as discriminatory against nonresidents.
Before the statement
The complaint says the Rosses received a conditional surcharge notice for their Manhattan cooperative unit.
After the statement
The joint pleading argues that nonresidents already pay property taxes and use fewer city services.
Ross v. New York: complaint challenging the pied-a-terre taxSuffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.Why this label?
Seeking to invalidate the surcharge expresses rejection of the tax, not merely disagreement with a description of it.
This label describes the statement's response within the context above.
 Zohran MamdaniMayor of New York CityDirectly involved
"collecting critical revenue to fund our parks, schools and libraries"
Defended or excusedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Mamdani defends the tax as a way to raise money for city services without shifting the burden onto working New Yorkers.
Before the statement
The mayor announces that property owners are receiving initial notifications.
After the statement
He commits to implementing the law and collecting the revenue.
Mamdani announces notices for the new pied-a-terre taxFirst quoted statement by Mayor Mamdani, beginning with his account of the city's fiscal challenges.Why this label?
He expressly supports imposing and collecting the surcharge.
This label describes the statement's response within the context above.
 Julie MeninSpeaker of the New York City Council
"This is a smart, sensible proposal"
Defended or excusedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Menin supports the proposal as a source of revenue for services and affordability measures without burdening working New Yorkers.
Before the statement
The governor announces the initial tax proposal.
After the statement
Menin also favors additional revenue from the highest earners.
Hochul announces pied-a-terre tax proposal for luxury second homesStatements by Kathy Hochul, Zohran Mamdani, Julie Menin and Brad Hoylman-Sigal.Why this label?
She explicitly approves the proposed second-home surcharge.
This label describes the statement's response within the context above.
Show fewer responses
 Brad Hoylman-SigalManhattan borough president
"This is about fairness"
Defended or excusedCase context: Should New York impose its pied-a-terre tax on New York City second homes?
Read more
Hoylman-Sigal supports the surcharge because wealthy second-home owners benefit from public services that protect their investments.
Before the statement
His statement appears in the governor's proposal announcement.
After the statement
He cites subways, schools and other services as benefits owners should help fund.
Hochul announces pied-a-terre tax proposal for luxury second homesStatements by Kathy Hochul, Zohran Mamdani, Julie Menin and Brad Hoylman-Sigal.Why this label?
He endorses the tax and supplies a fairness argument for imposing it.
This label describes the statement's response within the context above.
Sources
(7)
Original text
Ross v. New York: complaint challenging the pied-a-terre tax
Relevant passage: Suffolk index 628629/2026, NYSCEF document 2; paragraphs 1-19, 72-82 and 119-220; prayer for relief, page 39.
Excerpt
"This case arises out of Defendant’s attempt to enact and enforce a discriminatory property tax that falls exclusively on nonresidents of New York City, in violation of the state and federal constitutions. … These nonresidents, including Plaintiffs herein, already pay significant sums to the City in property taxes, the same taxes at the same rates paid by New York City residents occupying similarly assessed residential properties. … Article 30-C is therefore unconstitutional to the extent it purports to exclude PAT Tax revenues from the amount raised by tax on real estate for purposes of Article VIII, § 10(e)."
About this source
Joint pleading alleging unconstitutional discrimination and improper treatment of tax receipts. The plaintiffs' allegations and requested declarations are not a court judgment.
- Author
- Pillsbury Winthrop Shaw Pittman LLP, for Wilbur Ross, Hilary Geary Ross and Steve Wynn
- Published
- Accessed
Original text
O'Brien v. New York City: September 29 decision on tax notices
Relevant passage: Index 85217/2026, NYSCEF document 34; scope on pages 1-2; ordered relief on pages 21-22.
About this source
The order addresses the supplemental roll and mailed notices. It cancels the notices and requires individualized determinations before new notices. It does not declare the surcharge statute unconstitutional.
- Author
- Justice Wayne M. Ozzi, New York Supreme Court, Richmond County
- Published
- Accessed
Original post
Hochul defends the pied-a-terre tax after Ross and Wynn sue
About this source
Hochul adds her own defense of the tax to a reporter's account of the new lawsuits.
- Author
- Kathy Hochul
- Published
- Accessed
Official statement
Mamdani announces notices for the new pied-a-terre tax
Relevant passage: First quoted statement by Mayor Mamdani, beginning with his account of the city's fiscal challenges.
About this source
Mamdani defends collecting revenue for parks, schools and libraries while announcing the start of notifications.
- Author
- NYC Mayor's Office
- Published
- Accessed
Official statement
Hochul announces pied-a-terre tax proposal for luxury second homes
Relevant passage: Statements by Kathy Hochul, Zohran Mamdani, Julie Menin and Brad Hoylman-Sigal.
About this source
April proposal and attributed endorsements. Its proposed $5 million threshold should not be substituted for the enacted phase-one thresholds.
- Author
- Office of Governor Kathy Hochul
- Published
- Accessed
Original text
New York Tax Law Section 1353: surcharge rates
Relevant passage: Section 1353(a), phase-one rates; Section 1353(b), phase-two rates.
About this source
Statutory rate bands. Department of Finance market values are not interchangeable with an owner's purchase price.
- Accessed
Original text
New York Tax Law Section 1350: non-primary-residence surcharge
Relevant passage: Section 1350, imposition of surcharge and phase-one and phase-two thresholds.
About this source
Enacted provision imposing a surcharge from July 1, 2026. Eligibility depends on use of the property as a primary residence and its statutory market value.
- Accessed
Cite this record
- Publisher
- The Dispute Index
- Title
- Should New York impose its pied-a-terre tax on New York City second homes?
- First published
- Last updated
- Permalink
- https://disputeindex.com/cases/new-york-city-pied-a-terre-tax-nonresidents
The Dispute Index. "Should New York impose its pied-a-terre tax on New York City second homes?". First published: 2026-10-06. Last updated: 2026-10-06. https://disputeindex.com/cases/new-york-city-pied-a-terre-tax-nonresidents